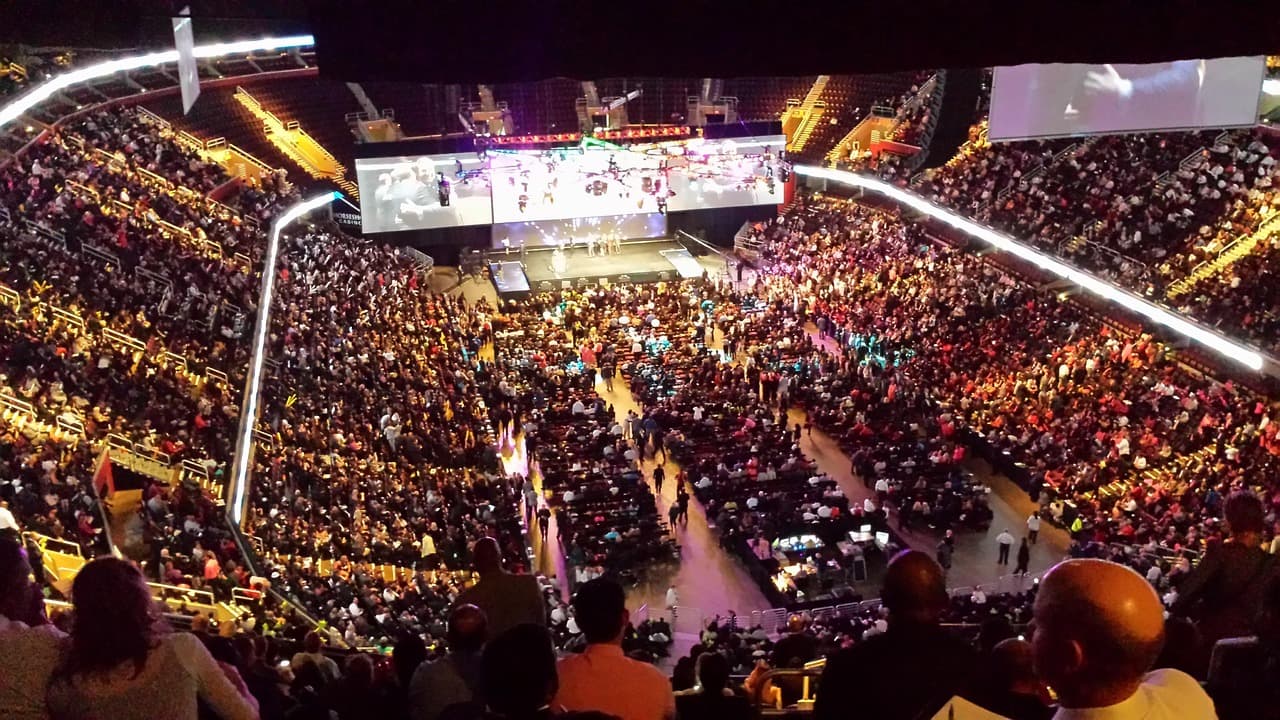
On 10 November 2026, the Banking Technology conference brought together leaders from banks, IT firms, regulators and fintechs for a full-day programme focused on how AI, agentic commerce and digital transformation are reshaping payments, product development and security. Speakers stressed that while technology is rapidly changing competition and customer experience, it also requires stronger regulatory compliance and organisational adaptation.
Key figures and trends
- According to the Magyar Nemzeti Bank (MNB), electronic payments in Hungary exceeded 50% of transactions; last year they surpassed 3 billion transactions in number and account for over 60% by value. In Budapest the share is around 70%.
- Mobile wallets account for roughly 30% of transactions, and the qvik payment system reached a 40% value share in online commerce.
- Retail flows to fintechs and neobanks grew strongly: between 2024 and 2025 flows to fintech providers expanded by more than 149%.
- A 1,048-person survey by 21 Kutatóközpont shows the mobile app is the primary digital banking channel for 70% of respondents, and the Digital Trust Index scored the domestic market 75 out of 100; Raiffeisen, UniCredit and CIB scored highest among banks with at least 30 responses (82 points).
Agentic commerce and the future of payments
Presentations by Juhász Katalin (Visa, regional head of product development) and Szincsák Gyula (Visa, senior product development expert) highlighted the rapid spread of agentic commerce, where AI agents drive shopping processes. Juhász outlined three development levels:
- Risk-free search and advice (AI suggests; humans decide)
- Agent assembles basket and fills checkout but final approval remains human
- Fully autonomous payments executed under prior/ongoing user authorisation
Most market solutions today operate at levels one and two, though there are live, more advanced examples (the Rohlik Group’s "Maja" assistant was cited) that can assemble baskets and initiate orders.
Szincsák argued that convergence and programmability will define payments’ future: users will express intent in natural language and transactions will execute automatically. That requires improvements such as agentic tokens, Click-to-Pay as a digital native credential, and digital identity-based verification (for example, instant age verification).
Cybersecurity: AI as both shield and weapon
Multiple panels examined new cyber risks introduced by AI. Participants included Biró Gabriella, Borókai Bence (OTP Bank), Galló Csaba Márton (CIB Bank), Halász Viktor (National Bureau of Investigation, NNI) and Luspay Miklós (MNB). They noted that AI brings novel threats (hallucinations, prompt injection, voice cloning) while also enabling defensive capabilities.
Concrete observations and risks:
- Language models can hallucinate, presenting false facts; excessive user trust in such outputs can be dangerous.
- Voice cloning from social media samples enables frauds where attackers impersonate relatives and coerce urgent transfers.
- Instances occurred where prompt injection embedded in incoming e-mails attempted to bypass internal controls; the attack was foiled only because data volume exceeded transfer limits.
- NNI tools can link darknet profiles by language and style traits, reducing online anonymity.
Panelists agreed that defence is not purely technological: it depends on customer awareness, proactive bank intervention to halt suspicious transactions, and a shift from static defence to resilience. Halász reported that roughly 25–30% of stolen sums can be recovered and investigations target criminal infrastructure such as accounts and servers.
AI agents and automated attacks
Marton László (SMP Solutions) argued that AI agents have become autonomous attack actors: in several incidents over the past year, AI executed large portions of attack chains independently. He expects near-term waves of partially or fully automated AI campaigns, weekly vulnerability spikes and self-propagating AI worms, and foresees AI-driven defence becoming essential in 3–5 years.
Recommended immediate steps include mapping organisational AI use, tightening privileges, adopting AI-assisted detection, updating incident response plans for AI-specific compromises and regular drills.
Digitalisation and the full customer journey: MNB expectations
Greinstetter Balázs (MNB, director for digitalisation) said the next phase of banking digitalisation requires not only digitising specific products but full customer journeys, back-office processes, data management and controlled AI application. The MNB emphasised high-quality linked data and modern backend systems as prerequisites for effective automation and AI value creation.
Business and organisational challenges
Speakers such as Treso Károly (Raiffeisen Bank International) and Kormos Benjámin (Clarity Consulting) stressed that AI adoption is primarily an organisational and human-capability challenge. The Pulze Digital programme’s experience shows training and role-based development are crucial: technology alone does not deliver business transformation.
Payment infrastructure and terminal platforms
Physical acceptance points are evolving: Android-based SmartPOS devices and integrated platforms (for example Maxstore in the SimplePay/HelloPay network) enable remote monitoring, app integration and bundled service offerings. Managing software updates and device fleets creates operational demands but reduces time to resolution and increases merchant satisfaction.
Conclusion
The Banking Technology 2026 conference concluded that AI and digital transformation are rapidly remoulding banking and the payments market in Hungary. Technology offers faster innovation, more personalised customer experiences and cost reductions, but also creates cyber, regulatory and organisational challenges. Success will depend on reliable data architectures, embedding programmability into product design, preserving customer trust and investing in targeted human capability development.


